Used Car and Motorbike Finance: Lenders, Costs and Example Instalments
If you want used car finance in South Africa, or finance for a used motorbike, it helps to know who lends, what each one asks for and what it costs.
Below you will find the main lenders, how marketplace finance works, example instalments on used bikes and the costs you should plan for.
Nothing on this page is a decision about your application. Each lender decides for itself, and the terms in its own agreement are the ones that count.
Who finances used cars and motorbikes in South Africa?
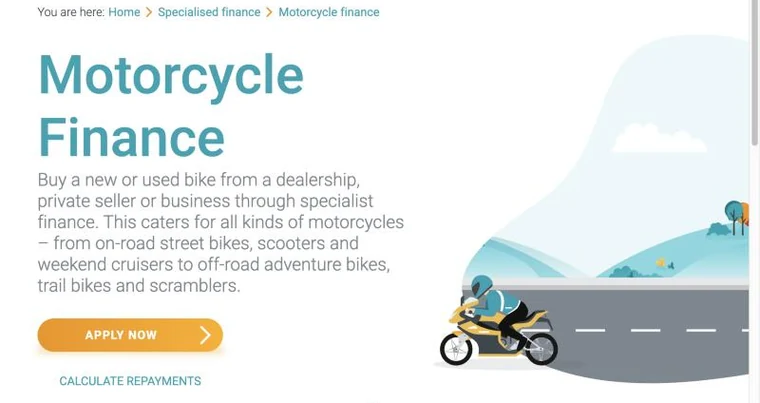
WesBank has a dedicated motorcycle finance page with a repayment calculator. It says you can buy a new or used bike from a dealership, a private seller or a business, and that the finance covers street bikes, scooters, cruisers, adventure bikes, trail bikes and scramblers. WesBank also offers private sale finance, and publishes guides on balloon payments and buying a used car.
MFC, a division of Nedbank, explains in its help centre that you can buy from an approved dealer or from a private seller through its private-to-private process. It says it cannot give pre-approved finance, because it needs your details and the vehicle’s details, and that its rate depends on a credit check, the type of asset and the deposit.
Absa lists vehicle finance for new or used vehicles on its car finance page. You can apply at an approved dealer, even if you are not an Absa customer. Ask whether it finances the motorbike you have in mind, because its page speaks mainly about cars.
Capitec offers an unsecured Vehicle Loan of up to R500 000 over up to 84 months for used or new vehicles, according to its page. You need a valid South African ID, you must be 18 or older, and you need your last three consecutive payslips. If your salary does not go into a Capitec account, you also need a bank statement that shows your last three salary deposits. An unsecured loan works differently from asset finance, so compare the total cost with a vehicle finance quote.
| Lender | What the lender says | Check before you apply |
|---|---|---|
| WesBank | Motorcycle finance for new or used bikes, from a dealer, private seller or business | Age and type of bike, deposit |
| MFC (Nedbank) | Dealer and private-to-private purchases, rate based on credit check, asset type and deposit | Whether your bike qualifies |
| Absa | Vehicle finance for new or used vehicles through approved dealers | Whether bikes are covered |
| Capitec | Unsecured vehicle loan up to R500 000, up to 84 months | Total cost versus asset finance |
Standard Bank and other banks also offer vehicle finance, so it is worth asking more than one lender. The same buyer can receive noticeably different offers, and a quote does not commit you to anything.
Dealer and marketplace finance: how WeBuyCars does it
Many buyers arrange finance where they buy. On its finance page, WeBuyCars says you can click “Get finance” on a vehicle, or visit a branch and speak to a finance and insurance agent. You need a valid driver’s licence and a South African ID or passport number, and foreign nationals can apply. It says rates start from prime and depend on your credit profile, the amount and the term.
Its page lists pre-approval within 24 hours and full approval usually within 2 to 3 business days once documents are in. It also says only Category A cars can be financed, and that cars whose manufacturer warranty has expired, or will expire within 6 months, need an extended or pre-owned mechanical warranty. These rules are described for cars, and the page does not say how they apply to motorbikes, so ask before you assume.
For vehicles that do not qualify for vehicle finance, WeBuyCars points to a Capitec personal loan. That is a different product with different costs, so treat it as a separate offer to compare.
What instalments on used motorbikes can look like
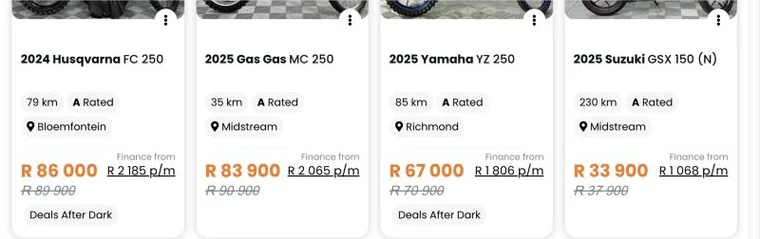
The WeBuyCars motorbike listings show a “finance from” monthly figure on each bike. We checked the page on 18 October 2026 and picked four examples to show the range. The site does not show the term, the deposit or the rate behind these figures, so your own offer will differ.
| Used motorbike (as listed) | Listed price | Finance from |
|---|---|---|
| 2016 Gomoto Xplore SI 150 | R13 900 | R669 per month |
| 2025 Suzuki GSX 150 (N) | R33 900 | R1 068 per month |
| 2025 Yamaha YZ 250 | R67 000 | R1 806 per month |
| 2024 Husqvarna FC 250 | R86 000 | R2 185 per month |
These are listing figures from one seller, not a quote from any lender. Use them to get a feel for the scale of instalments, then ask the lender for an illustration that shows the term, the interest rate, the fees and the total repayable.
Costs beyond the monthly instalment
Budget for insurance, licence and registration, roadworthy and delivery costs, servicing and tyres. On its finance page, WeBuyCars lists a licence and registration fee of R2 450 for vehicles under 3.5 tons and a delivery fee of R4 200 including VAT, and says the delivery fee covers getting the car ready, including roadworthy and inspection fees.
Ask every seller for the full list of fees in writing, and add them to your own budget. A cheap instalment on a vehicle that is expensive to insure or maintain can still strain your month.
How to compare offers: deposit, balloon and total cost
Use the same price, the same term and the same deposit so the offers can be compared fairly.
Cars.co.za suggests asking for both, because a deposit can change the instalment and the approval.
A balloon lowers the instalment but leaves a lump sum at the end.
Look at the interest, the fees and the total, not only the monthly figure.
The National Credit Act requires the agreement to show the cash price, deposit, loan amount, interest, fees, monthly payment and total repayable, and Cars.co.za says you can settle early without excessive penalties, which can reduce the interest. Its guide, No-deposit car finance: what you need to know, was published on 3 October 2025.
Before you sign on a used vehicle
WesBank’s used car buying tips suggest checking the service history and the vehicle identity number (VIN), which you can find on the licence disc, and finding out whether the vehicle has been in an accident. It adds that a vehicle is not necessarily a bad deal because of an accident, but you should know about it and weigh it up.
For a used motorbike, ask the seller for the service records and the registration papers, and check that the details match. If something does not add up, ask for it in writing or walk away. Never pay a deposit to a private seller before you have seen the vehicle and the paperwork.
Documents to have ready and where to get help
Most lenders ask for a valid South African ID or passport, your driver’s licence, recent payslips or proof of income, recent bank statements and proof of residence. Self-employed applicants are usually asked for more documents. Having everything ready makes the assessment faster.
You are entitled to one free credit report a year from the credit bureaus, according to the National Credit Regulator. Check it before you apply and correct any mistakes. If you think a lender has treated you unfairly, you can complain to the National Credit Regulator on 0860 627 627.
This is an independent information website. We are not a lender, credit provider, dealer or financial adviser, and we are not affiliated with WesBank, MFC, Nedbank, Absa, Capitec, WeBuyCars or the National Credit Regulator. We cannot tell you whether you will be approved, and nothing here is an offer of credit. Rates, terms and rules differ between lenders and change over time, so confirm every detail with the lender before you sign. Information was checked against official sources on 18 October 2026.